

FHSA vs. HBP: Which to Use First When Buying a Home
Saving for your first home is exciting, but it can also feel overwhelming. Between building a down payment and figuring out a mortgage, the last thing you want is a confusing set of rules.
The good news is that the government offers two tools that can help first-time buyers: the First Home Savings Account (FHSA) and the Home Buyers’ Plan (HBP). They sound similar, but they work in very different ways. And if you can use both, the order you use them in can matter.
Here is a simple guide to what each one does and how to think about which to use first.
What Is the FHSA?
The First Home Savings Account, or FHSA, is an account designed to help you save for your first home. It has three features that make it stand out:
-
Your contributions are generally tax-deductible. When you put money in, you can lower your taxable income for the year, much like an RRSP.
-
Qualifying withdrawals are tax-free. When you take the money out to buy your first home, you pay no tax on it.
-
There is nothing to pay back. Once you use the money for your home, it is yours.
So the FHSA gives you a tax break going in and a tax-free withdrawal coming out. That is a rare combination.
There are annual and lifetime contribution limits set by the government, and they can change over time. You can check the current figures on canada.ca or in your CRA My Account.
What Is the Home Buyers’ Plan?
The Home Buyers’ Plan, or HBP, works differently. It is not a separate account. It lets you withdraw money from your RRSP to help buy your first home, and you must repay it over time.
Here is the key part: the HBP is a withdrawal from your RRSP with a repayment requirement. You take the money out without paying tax up front, but you have to pay it back into your RRSP over a set repayment period set by the government.
If you do not repay the required amount in a given year, that unpaid portion gets added to your income for that year, and you pay tax on it. So while the withdrawal itself is not taxed up front, there is a string attached: you must put the money back.
There is a maximum HBP withdrawal amount set by the government, and your repayment schedule starts a set number of years after you take the money out.
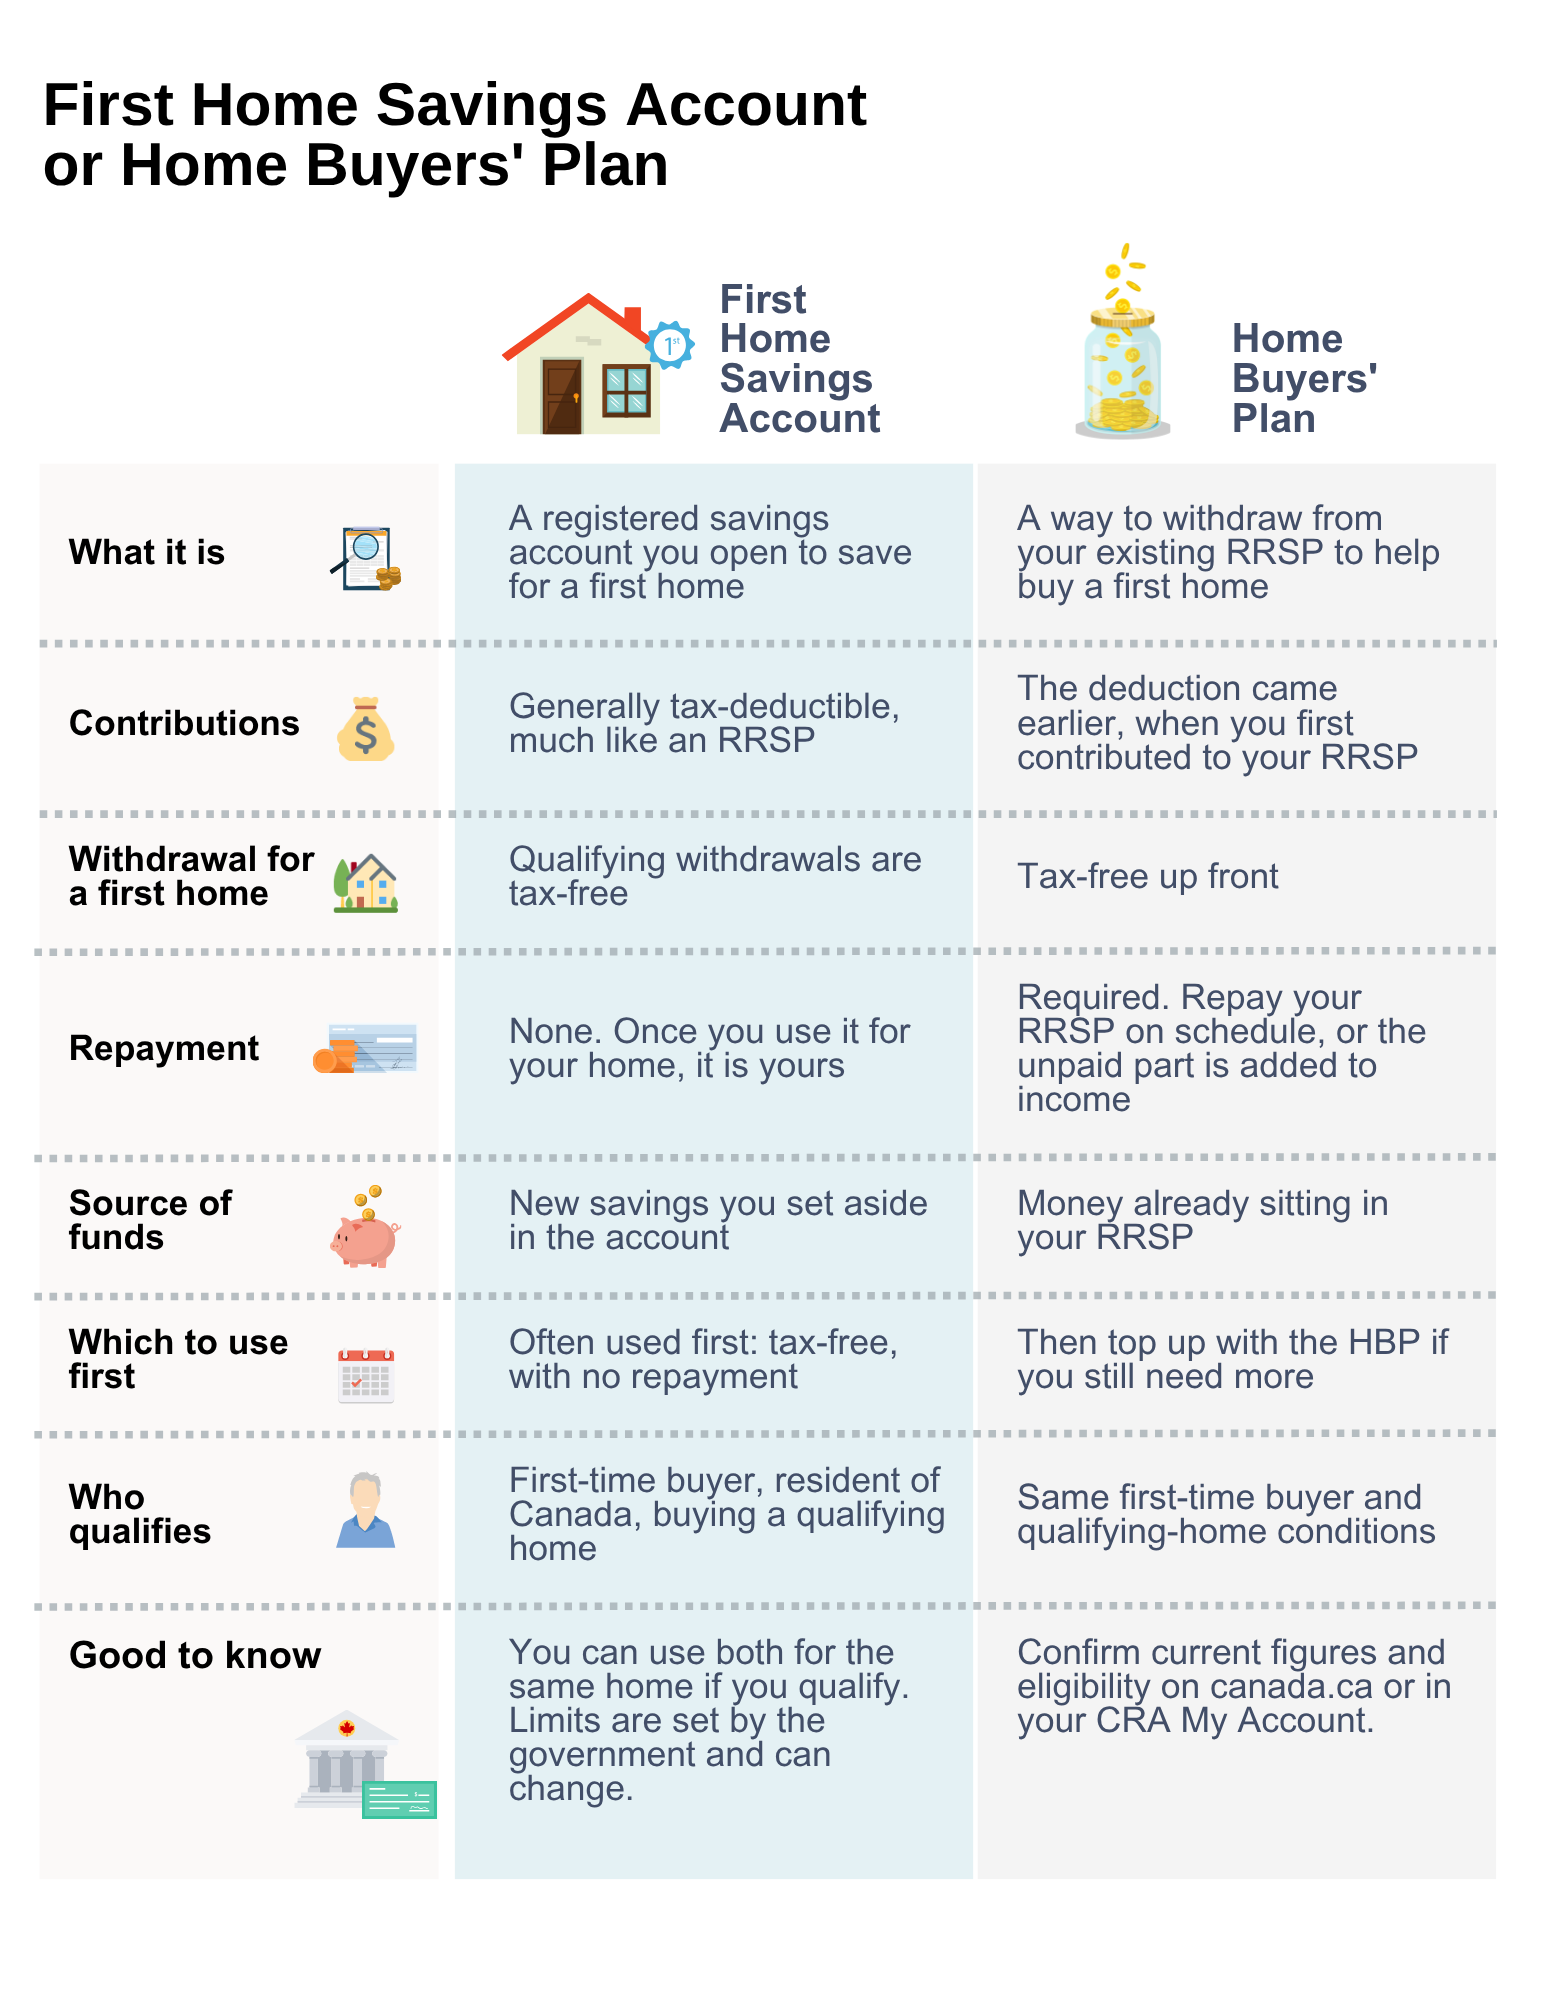
The Core Differences
When you line them up side by side, a few differences stand out.
-
Tax deduction. Both can give you a deduction. FHSA contributions are generally deductible. With the HBP, the deduction came earlier, when you first contributed to your RRSP.
-
Repayment. The FHSA has none. The HBP must be repaid to your RRSP, or the unpaid part is taxed as income.
-
Tax-free vs. repayable. An FHSA qualifying withdrawal is truly tax-free. The HBP is a withdrawal from your RRSP that you must pay back.
-
The account itself. The FHSA is a registered savings account you can open if you qualify. The HBP uses money already sitting in your RRSP.
In short, the FHSA gives you money you never have to repay. The HBP gives you access to your RRSP savings, but only if you pay it back on schedule.
Can You Use Both? And Which Comes First?
Yes, if you qualify, you can use both the FHSA and the HBP for the same home purchase. Many first-time buyers do exactly that to pull together a larger down payment.
So which should you reach for first? A common approach is to use the FHSA first. The plain-language reason is simple: an FHSA qualifying withdrawal is tax-free and does not have to be paid back, so many buyers draw on that money before tapping the HBP.
A common approach looks like this:
-
Use your FHSA savings first, since that money is tax-free and repayment-free.
-
Then use the HBP to top up your down payment if you still need more, drawing on your RRSP.
This way you use the repayment-free money first, and you only take on the HBP’s repayment commitment for the amount you actually need. The right order depends on your situation, including how much you have in each account and what your budget allows.
Who Qualifies?
Both tools are built for first-time home buyers, and the rules have a lot in common.
In general, you must meet the CRA’s first-time home buyer and qualifying-home conditions. Typically, that means you have not lived in a home you or your spouse/common-law partner owned during the CRA lookback period, and you must be a resident of Canada buying or building a qualifying home for yourself.
These rules have specific conditions and dates, so check the current details on canada.ca or through your CRA My Account before you make a withdrawal. That way you can confirm you meet the conditions and see the latest limits.
Putting It Together
Saving for a first home is a big goal, and these two tools can move you closer to it. The FHSA gives you a tax break going in and tax-free money coming out, with nothing to repay. The HBP lets you withdraw from your own RRSP, as long as you pay it back on schedule.
If you can use both, leading with the FHSA and topping up with the HBP is a simple way to make the most of each. Take a few minutes to look at what you have saved in each account and where the current limits sit, and you will be in a strong spot to plan your down payment with confidence.
This content is provided for general informational purposes only. It is not intended to provide investment, tax, or legal advice, and should not be relied upon as such.
Sources: